

Meet our local Lake District Team at Lakelovers
Thinking about holiday letting? You deserve the peace of mind that your property is in expert hands. At Lakelovers,...


by Lakelovers / Owner Hub
If you let your property to paying guests, regular home insurance won’t cover you. You need specialist holiday let insurance, which usually combines buildings and contents cover with public liability insurance. If you employ anyone to help, such as a cleaner or gardener, employers’ liability insurance is a legal requirement too.
Insurance can feel like a maze, and getting it wrong can leave you with a big bill when something goes wrong. We’ve been helping Lake District owners let their homes for over 25 years, so we’ve put together this friendly guide to the cover you need, what it typically costs, and the questions owners ask us most.
Thinking of letting your Lake District home?
Get our free Owner Guide and a chat with our local team, or get a specialist holiday let insurance quote from our partner Pikl.
Holiday let insurance isn’t a legal requirement in itself, but going without it leaves you exposed to the cost of damage, accidents and lost bookings. Here’s what a good policy usually includes, and what you’ll want to check.
Buildings cover protects the structure of your holiday home: the walls, roof and permanent fixtures such as your kitchen and bathroom.
You’ll need to know what it would cost to rebuild your property. This is often different from what it would sell for, so it’s worth getting right. A chartered surveyor can help you work it out, or speak to your mortgage lender.
Got a mortgage? Your lender may insist on buildings insurance and may have other requirements for a holiday let, so give them a call and check.
In a holiday let, it’s not just the building you need to protect. Contents cover protects your furniture and belongings against things like fire, theft and damage. You can buy it on its own or as part of a holiday let policy.
Guest damage is where specialist cover really matters. Look for a policy that covers accidental or malicious damage and theft by paying guests, as standard policies often don’t.
Public liability covers you if a guest or visitor is injured at your property and makes a claim against you. It’s essential for any holiday let, and at Lakelovers we ask all our owners to have at least £2 million of public liability cover.
Many Lake District homes have plenty of character, which can mean steep staircases, low beams or slate floors that get slippery when wet. If your property has features like these, or a hot tub or pool, check the small print to make sure your level of cover is right.
If you employ anyone to help look after your holiday let, even just one cleaner, gardener or maintenance person, employers’ liability insurance is a legal requirement. According to GOV.UK, you must be covered for at least £5 million, and you can be fined £2,500 for every day you’re not properly insured. There are some exemptions, for example if you only employ close family members.
If a fire, flood or burst pipe leaves your property unusable for a while, you may have to cancel bookings. Loss of rent cover helps make up the income you’d lose. If you rely on your letting income, it’s well worth considering.
| Type of cover | What it protects | Do I need it? |
|---|---|---|
| Buildings | The structure, roof and permanent fixtures | Strongly recommended, and your mortgage lender may require it |
| Contents | Furniture, belongings, and damage or theft by guests | Strongly recommended |
| Public liability | Claims if a guest or visitor is injured | Essential. Lakelovers owners need at least £2 million |
| Employers’ liability | Claims from anyone you employ, such as a cleaner | Required by law if you employ staff (minimum £5 million) |
| Loss of rent | Lost booking income if the property can’t be used | Optional, but worth it if you rely on the income |
The cost depends on the cover you choose and your property. As we explain in our guide to the costs of running a holiday let, these are typical starting points:
| Type of policy | Typical cost per year |
|---|---|
| Standard buildings and contents | From around £150 |
| Holiday let cover including public liability | Typically £300 to £600+ (averaging around £357 in 2026) |
To get cover that’s tailored to your holiday home, Lakelovers and the Sykes family of brands have partnered with Pikl Insurance*, specialists in holiday let insurance.
Thinking about letting your Lake District home?
Request your free Owner Guide and our local Lakes team will be in touch.
Your holiday let is most at risk when it’s empty for long stretches. In a Lake District winter, a leak or burst pipe can go unnoticed for days in an empty property.
Many policies have limits on how long a property can be unoccupied before cover is reduced or conditions apply, often around 30 days. Check your policy for:
If you’re planning a quiet spell over winter, let your insurer know in advance.
Before you buy or renew, run through these questions:
Most owners need specialist holiday let insurance covering buildings and contents, plus public liability insurance. If you employ anyone, employers’ liability insurance is a legal requirement. Loss of rent cover is optional but useful if you rely on the income. Lakelovers owners need at least £2 million of public liability cover.
It depends on your policy. Many insurers limit how long a property can be unoccupied, often around 30 days, before cover is reduced or extra conditions apply. Check your policy and tell your insurer about any long empty periods.
Check that your liability cover includes hot tubs and pools, as some policies don’t. You may need to pay extra to include this cover.
Only if your policy includes it. Standard home insurance often won’t cover damage by paying guests, so look for a specialist holiday let policy that includes accidental and malicious damage, and theft, by guests.
Yes. However you take bookings, through an agency, a platform like Airbnb or direct with guests, you’re letting your property to paying guests, so you still need the right cover. Tell your insurer how you take bookings and check the policy covers all of them. Don’t rely on a booking platform’s host protection in place of your own insurance.
Holiday let insurance itself isn’t a legal requirement, but employers’ liability is if you employ staff. Your mortgage lender may also insist on certain cover, and GOV.UK guidance advises holiday let owners to have dedicated holiday let insurance, public liability cover, and buildings and contents cover suitable for short-term letting.
Insurance is just one part of running a successful holiday let. These guides will help with the rest:
Whether you’re just starting your holiday letting journey or ready to take bookings, our friendly local team is here to help. Request your free Owner Guide and we’ll talk you through everything, from insurance to what your Lake District home could earn.
Thinking about switching agents or listing your property for the first time? Call our local Lakes team on 015394 88855 or complete the form below to request your FREE Owner Guide.
You can also email newowners@lakelovers.co.uk or visit our Let Your Cottage page.
This guide is for general information only and isn’t financial or legal advice. Insurance policies vary, so always read the terms and conditions of any policy before you buy. As a holiday let owner, you’re responsible for having suitable insurance in place.
*Sykes Cottages Ltd is an Introducer Appointed Representative of Pikl Insurance Service Limited Registered Number 10449346 who are authorised and regulated by the Financial Conduct Authority firm number 773457. Registered Office: Suite B, 2nd Floor, The Atrium, St Georges Street, Norwich, England, NR3 1AB.
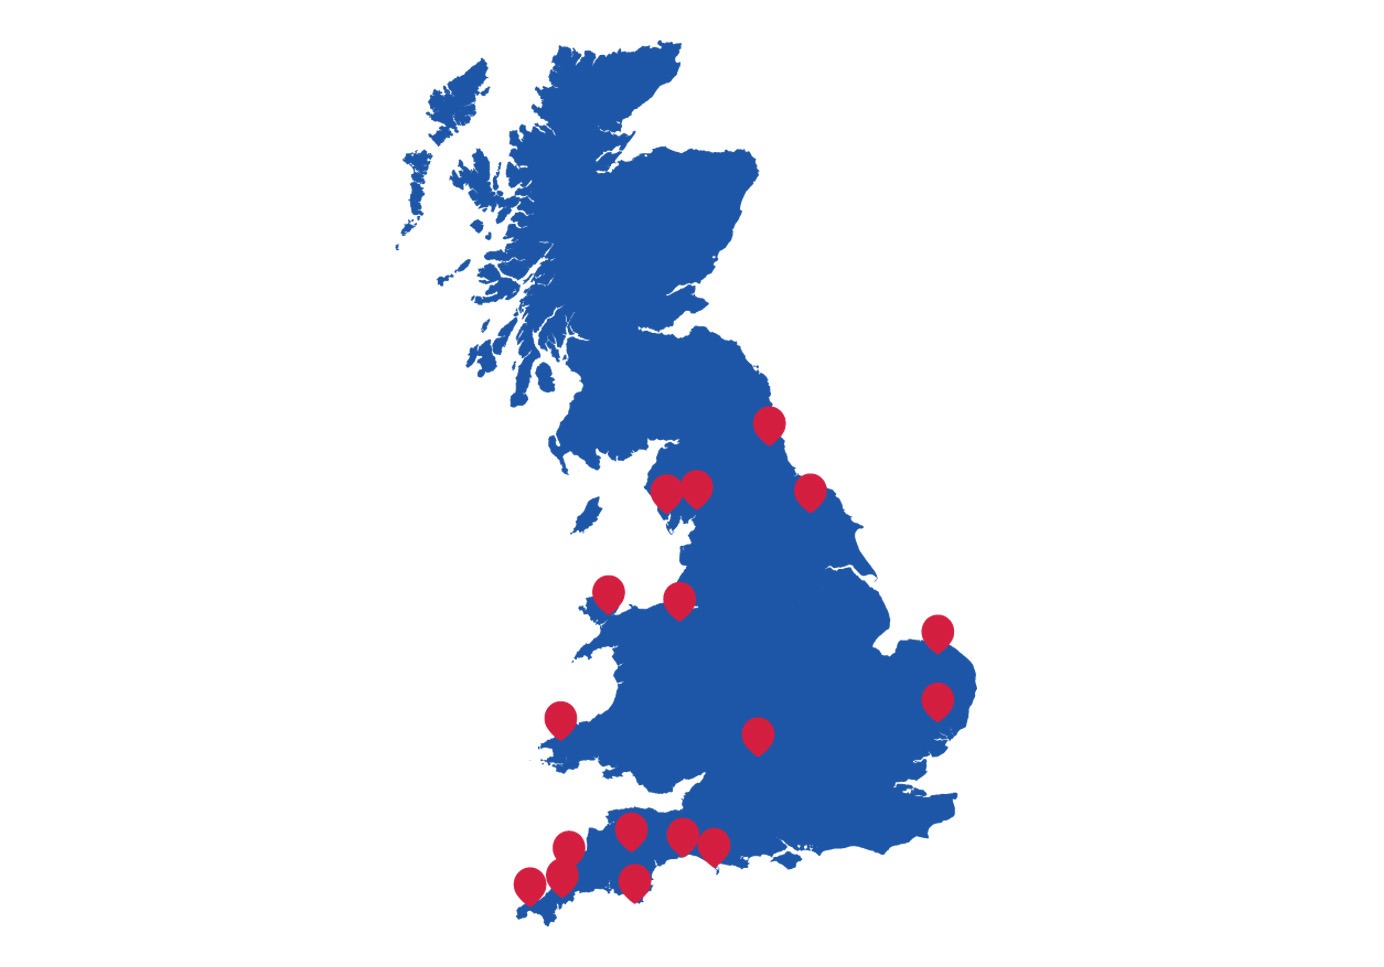
Interested in letting a property outside of the Lake District? We’re proud to be part of Sykes Holiday Cottages, with a network of regional brands offering the same award-winning service across the UK. Enquire now to be put in touch with your local holiday letting experts.
Find out how we can work together. With over 25 years’ experience, our local expertise will give you peace of mind and bring you the bookings you deserve.
by Lakelovers / Owner Hub

Sign up to receive exclusive offers, competitions and the latest news to your inbox, and you'll be entered into our monthly prize-draw 3 times!

Thinking about holiday letting? You deserve the peace of mind that your property is in expert hands. At Lakelovers,...
The end of the Furnished Holiday Let (FHL) tax regime in April 2025 changed the rules for holiday let...
The Lake District has long been one of the UK’s most desirable locations for owning a holiday home. With...

